Author: daniel

  • Scotts Square Residence – the great choice for city dwellings (8 Scotts Road)

    Scotts Square Residence – the great choice for city dwellings (8 Scotts Road)

    Scotts Square Residence is the go-to freehold condo for those looking for luxury living with great features like a rooftop infinity pool. We doubt anyone would regret this high purchase price, as the rooftop pool excels any outdoor fun.
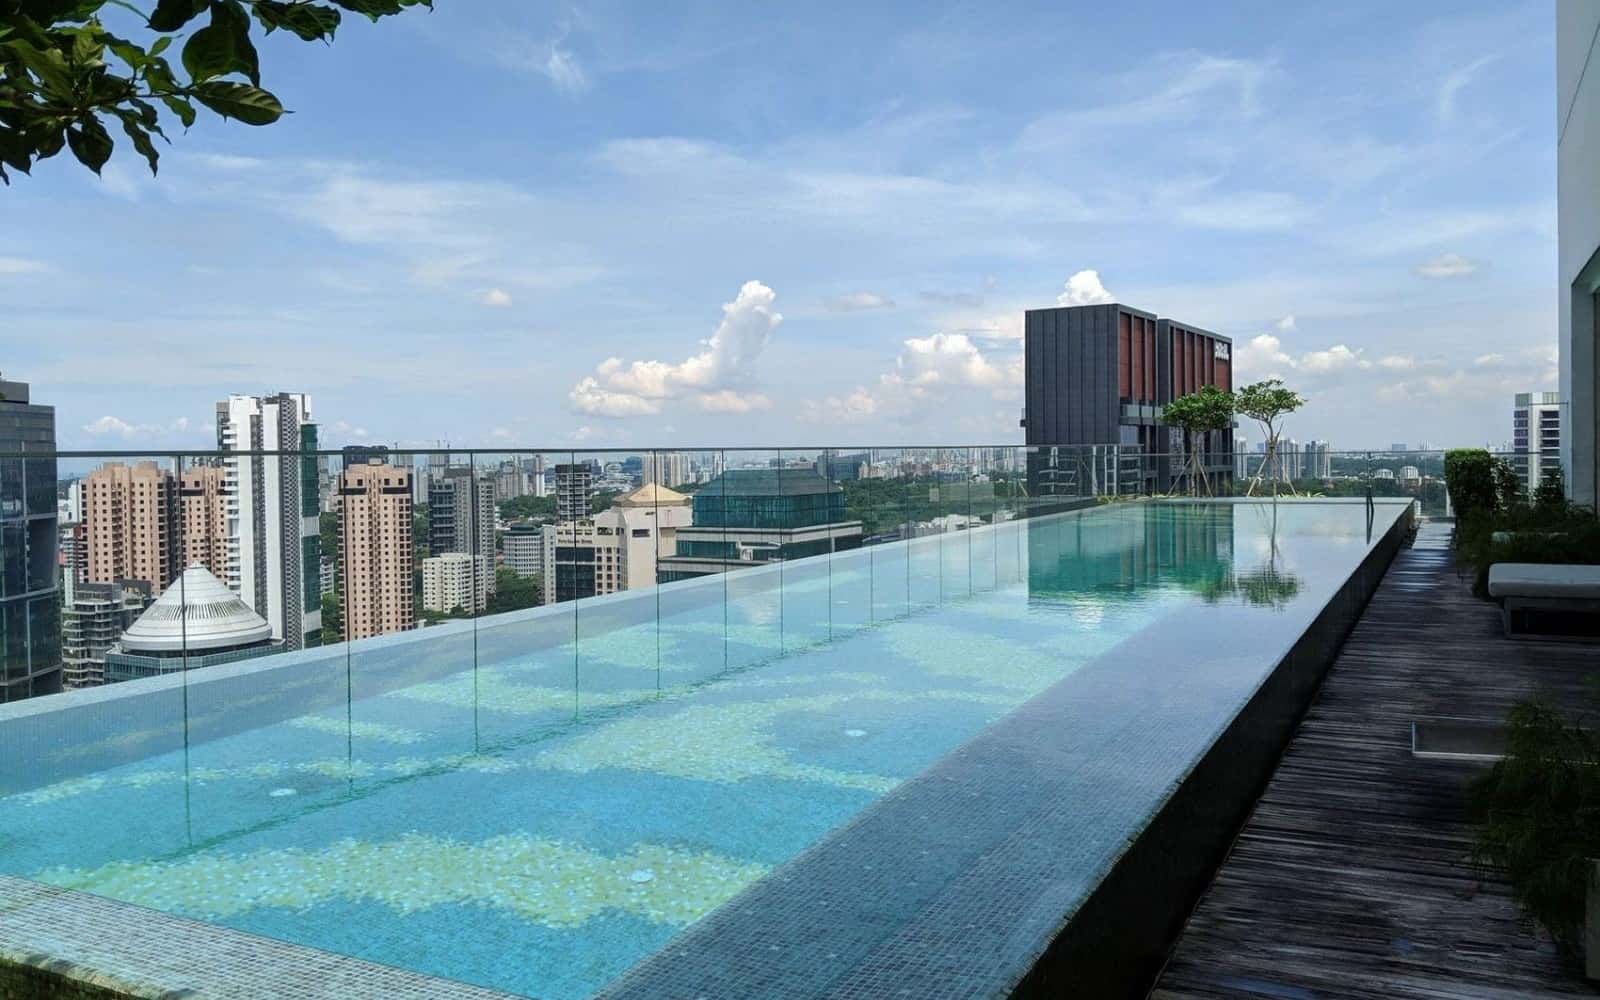
    Scotts Square Inifinity Pool

    if you’re looking for a luxury condo near Orchard Road shopping belt, then Scotts Square residence will be perfect for you. Freehold condominiums are hard to come by along the main road, but there are some other options such as Lucky Plaza Apartments and to a certain extent Orchard Towers.

    None of which are synonymous with luxury or have any facilities to speak of. Of course, the more famous luxurious option would be the Orchard Residences, but this is a 99-year leasehold property. So, if you’re looking for freehold status, modern living, and to be right on Orchard Road, you really only have one prime candidate here: the Scotts Square condo.

    One of the great things about the Scotts Square condo is that you’re just a short walk to MRT. Coming out of the development gives you access via an underground passage to Tangs Plaza, where you can get into the MRT station. Perhaps the only downside here would be that if it’s raining, you will need your umbrella for the walk to Tangs. In the future, once the Thomson-East Coast Line is up, the connectivity will be improved even further, with the construction site right next to Ion.
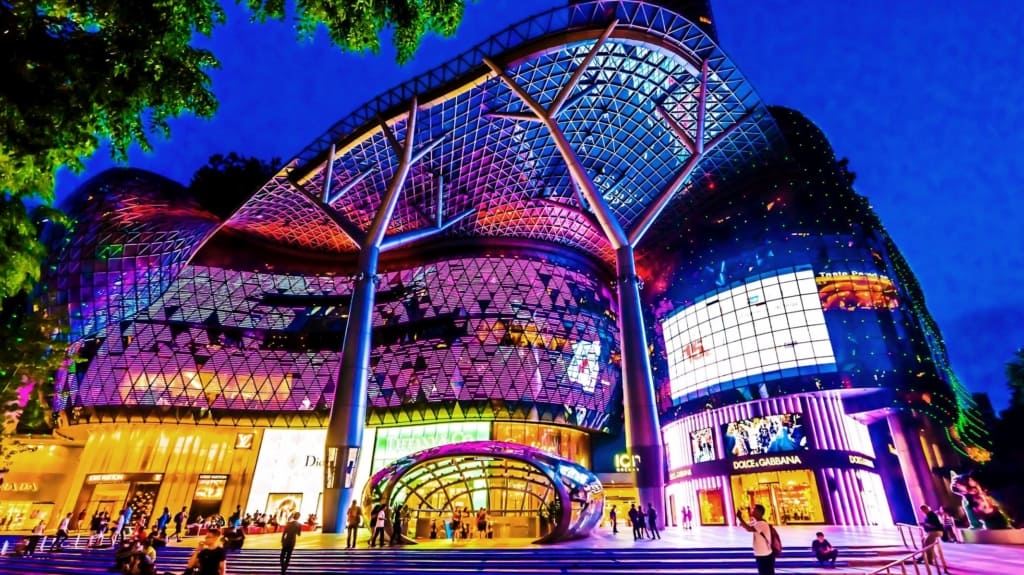
    Scotts Square Condo for Sale

    One last potential downside of the location of Scotts Square condo is the proximity to schools. There are two international schools within walking distance of the condo, namely International Schools Singapore (ISS) and Chatsworth International School. In terms of good local schools, Raffles Girls’ School, Singapore Chinese Girls’ School and Anglo-Chinese School are not too far off, but they’re not close enough to walk to either.

    For parents with younger children, there are MindChamps Preschool at Paragon and Pat’s Schoolhouse at Claymore, both within walking distance. However, considering the unit sizes and development, we do not think this will be an issue for most prospective buyers as the Scotts Square is really more for investors and couples without children or older, more independent children.

    Scotts Square residence has a perfect rectangular shape, this is beneficial because it’s close to the ERP but also close to the Orchard Shopping Belt. Unfortunately, there is no access to the lower levels of the building from the back – only a pedestrian entrance at Nutmeg road. For a prime city development, this is really good enough. One potential drawback of this location would be the traffic flow in and out of the building. The building is located near a pedestrian crossing, which could cause traffic to build up during peak hours.

    We were quite surprised by the size of each unit for a prime condo complex, especially because new launches over the past few years have been at 500 square feet or more. The private lift lobby does take up some space, but it is still very liveable. However, there are no penthouse apartments, with the biggest apartment coming in at 1249 square feet. So, if you need more space than a three-bedroom, the Scotts Square condo would not be able to accommodate your needs.

    When you arrive at the condo, it’s hard not to notice how spacious and welcoming the drop-off point is right in the middle of Scotts Square. It feels like you’re pulling up to a hotel in a big city!

    Located in the entrance to the building at the lobby is where you can instruct deliveries to be sent in the event that you are not home. You can collect these when you get back. This should come in handy for many people

    Scotts Square probably has a higher average selling price than a luxury condo in a different area, but not so much if you compare it to other places in this area, such as Twentyone Angullia Park and Ritz-Carlton Residences. Additionally, you have to take into account that the Scotts Square condo is in the most prime location and the most convenient as well.

    For sale, Scotts Square units were once priced as high as $4, 803 PSF. With time and lower demand, apartments now average at around 40% of those prices so they’re much more affordable today. Additionally, the unit size at Scotts Square are substantially smaller than that of TwentyOne Angullia Park Residence and the Ritz-Carlton Singapore. It means that for a more affordable quantum you can also get a better value.
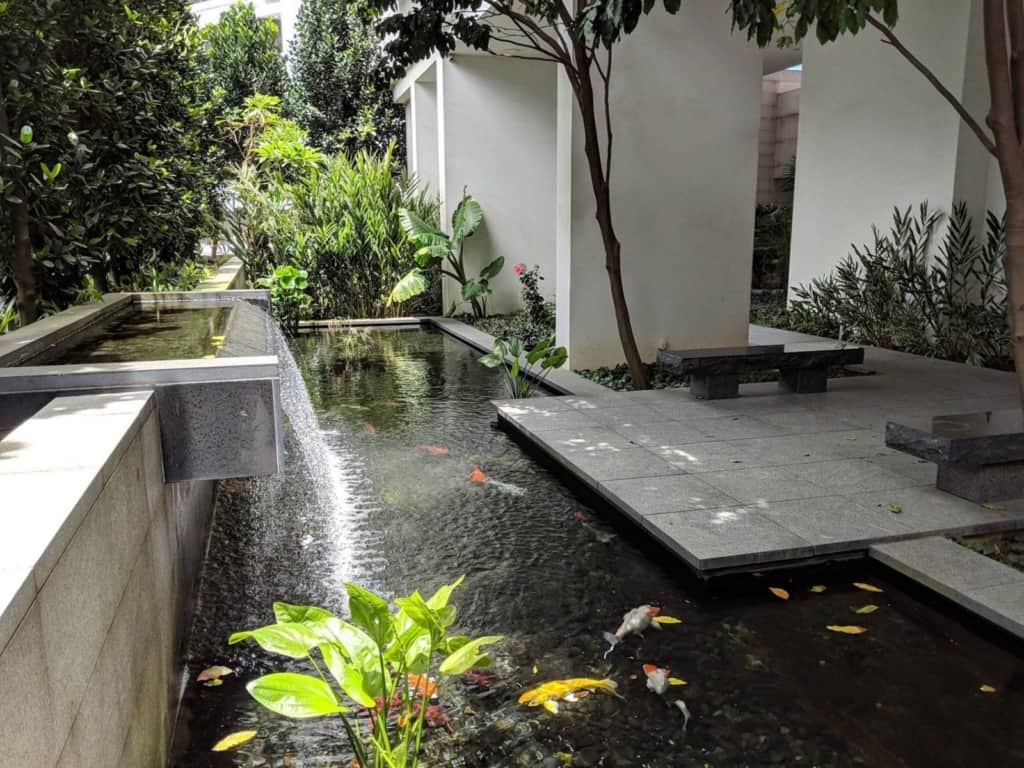
    We think that the Scotts Square condominium is an impressive development if you’re looking for luxury urban living. The views of downtown are unparalleled, and the amenities are also top-notch.The location is beautiful and the facilities are among the best you’ll find. The lobby area, pool, gym and private elevator to each unit are just the icing on the cake. The garden has obviously been maintained meticulously over the years. It only received TOP last year, but it looks like it could have received that award anytime within the last decade.

    If you’re a fan of the hotel experience, then this development will be right up your street. they put a lot of thought into the design and everything screams quality. As always with a city condominium, if you are fine with the smaller unit sizes and hustle and bustle in Orchard Road, this is quite a special oasis in town that you just have to visit for yourself.

    With a city condominium, there are many small units and a bustling lifestyle. If you are fine with these aspects of the condo, the Scotts Square Residences in Singapore is a special oasis.
  • Demand grew for larger spaces in prime non-landed and landed homes

    Demand grew for larger spaces in prime non-landed and landed homes

    PRIME NON-LANDED RESIDENTIAL


    The luxury market awakened by private wealth

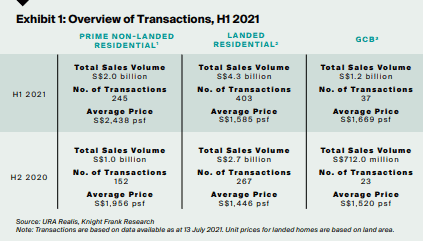
    • In H1 2021 alone, the prime non-landed residential segment recorded a flurry of deals amounting to S$2.0 billion, the highest since H2 2010 where sales within the luxury market segment totalled some S$2.4 billion. Rebounding from the pandemic-led recession last year, the sales activity in H1 2021 was double the amount of S$1.0 billion registered in the later half of 2020, and surpassed the S$1.7 billion transacted in the whole year 2020.
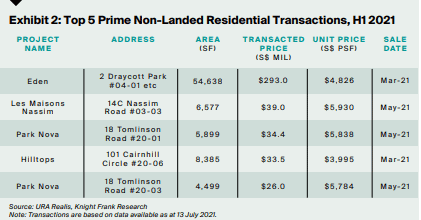
    • As the pandemic changed the priorities and preferences of home purchasers, with many leaning towards larger floorplates to accommodate for both living and working in the comfort of their homes, demand for larger non-landed homes in the prime districts increased. Notable deals included the sale of all units at Eden by Swire Properties for S$293 million or at an average of S$4,827 per square foot (psf).
    • Both foreign and local homebuyers/ investors were looking to penthouses or larger units with more than 3,000 square feet (sf) from the newly-launched Park Nova and Midtown Modern, as well as in the resale market.

    Market outlook

    • There are early signs that Singapore’s attractiveness to foreign and local private wealth is just beginning to translate into increased activity supporting prices, given the stable business and political environment when measured against political tensions in other parts of Asia.
    • With the current limited inventory of large luxury homes in the Core Central Region (CCR) coupled with the expected pent-up demand arising from prospective high-net-worth foreign buyers once travel measures ease, prices of these houses within the prime vicinity are expected to rise in the later half of the year.

    LANDED RESIDENTIAL

    Landed homes red hot amid the pandemic

    • Based on real estate statistics from URA, the Property Price Index (PPI) of private landed residential homes decreased slightly by 0.3% quarter-on-quarter (q-o-q) to 184.8 in Q2 2021, but grew by 8.5% year-on-year (y-o-y). The latest marginal decline brought the total price index gain in the first six months of the year to 6.3%.
    • According to the Census of Population 2020, over the past decade, the average total household income from work rose from S$7,812 in 2010 to S$10,608 in 2020. The proportion of resident households earning an income of at least S$9,000 and above expanded from 29.7% in 2010 to 44.2% in 2020, with the proportion of those earning S$20,000 and above doubling to 13.9% in 2020 from 6.6% ten years ago. The increasing disposable income and earning power provide a fundamental economic base where more households are able to transit to landed houses.
    • Following the uptick in sales in the later half of 2020, a total of 403 units above S$5 million was sold in H1 2021, translating into some S$4.3 billion. The demand was primarily driven by home upgraders looking to move into larger accommodations, especially in close proximity to reputed schools, as well as residents selling their private homes at higher prices due to an active and robust private home market, driven in part by the nouveau riche from the technology, pharmaceutical and finance sectors. These also simultaneously resulted in a thriving Good Class Bungalow (GCB) market segment, with 37 transactions of such houses amounting to S$1.2 billion. This was higher than the previous peak of about S$1.1 billion in H1 2010 as the asset class remains coveted and well-sought after by the growing number of ultra-high-net-worth Singaporeans and newly minted citizens.

    Market outlook

    • Landed housing captured the housing headlines of late, especially with the interest in GCBs. Many high-net-worth individuals, especially those who have converted to Singapore citizens, would be attracted to landed homes of larger floor areas and close proximity to amenities such as parks.
    • In addition, retired elderly landed home owners form a ready pool of sellers, incentivised to take profit and downgrade as they grow older and the cost to upkeep such properties become more burdensome.
    • As such, Knight Frank envisages the landed market segment to see continued interest and activity in the rest of the year, with prices moving upwards led by GCB sales. The GCB market, which came alive after the circuit breaker of 2020, is expected to enter into a period of renaissance in the next 12 months, as pandemic-driven entrepreneurship and transformative COVID-19 industries creates new wealth and a new class of luxury home buyer.

    Would like more of these information? Click here to receive a regular update through your Whatsapp or email today!

  • Shophouse sale on the rise!

    Shophouse sale on the rise!

    Total shophouse transaction values reached S$836.1 million in the first half of 2021, a 29.9% increase compared to the corresponding period last year. From a low of S$117.0 million in Q2 2020, total transactions have since rebounded to S$365.4 and S$470.7 million in Q1 and Q2, respectively.

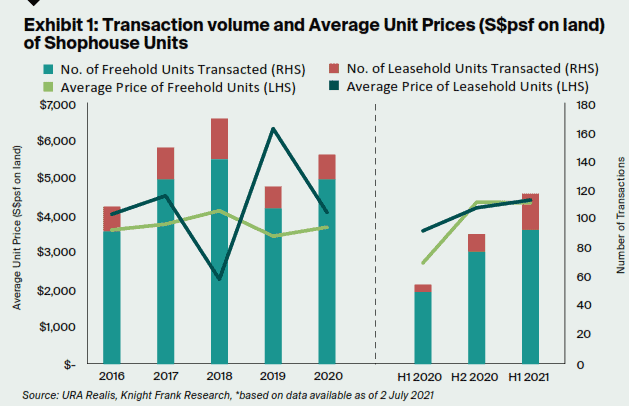
    There were 118 transactions in H1 2021, exceeding the 90 in H2 2020 and the last recent high of 99 in H1 2018 (Exhibit 1). While freehold shophouses (78.8%) still account for the bulk of transactions in H1 2021, leasehold sales volume more than double from H2 2020 to 25 units.

    Buyers who were drawn by prospects of capital appreciation bought leasehold properties in better-located districts. With over half of the leasehold transactions in District 2, Tanjong Pagar, this prime area has retained its popularity among buyers.

    Our shophouse-based neighbourhoods are very valuable, and they continue to be highly sought-after. The Little India district saw the highest transaction volume of shophouses in the first half of this year, with 26 being sold.

    The average sale price for shophouses in District 8 was at S$4.2 million. This neighborhood was a popular area for investors looking to enter the shophouse market, with the average price being less than S$5 million. Also, in District 15, the average sales price was just under S$4.5 million. This is an attractive result for investors who want to enter the shophouse market, with average prices well below the price of the area before redevelopment.

    Shophouses in the historic districts of Singapore have become very highly sought after. For example, they are still bought and sold with considerable interest in the two main districts, primarily due to their prime locations. The average price of a shophouse sold in District 1(Raffles Place, Cecil, Marina, People’s Park) and 2 is S$11.5 million, a figure expected to rise as more are sold.

    Shophouse sale chart

    While prices of freehold shophouses declined slightly in the first quarter of the year, this represents a 59.5% increase over the same time last year when Singapore was grappling with COVID-19. On average, leasehold prices for land increased by 4.9% in the first three months of the year. This was due to a surge in transactions in the Tanjong Pagar area, fetching higher prices.

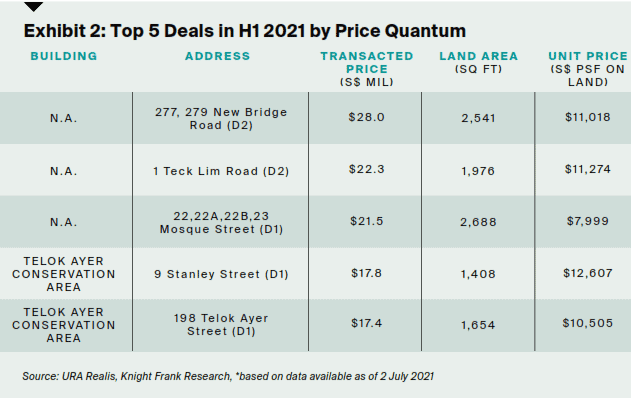
    About 56.8% of the shophouses sold in the first half of 2021 were above S$5 million, a higher proportion against the 42.2% in H2 2020. There is a high demand for high-end shophouses, and this demand is being met by a small number of premium properties that are well-suited to the market.

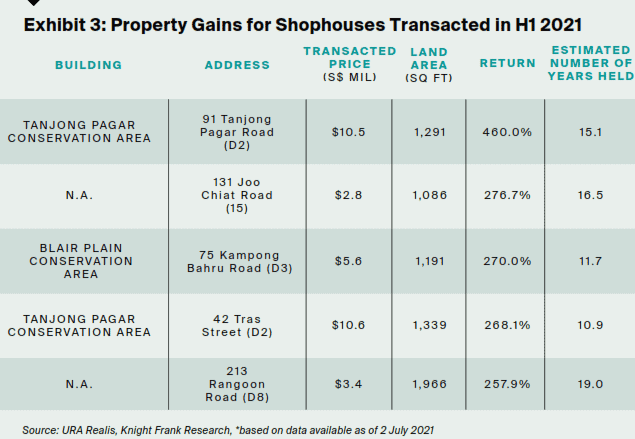
    At 91 Tanjong Pagar Road, a shophouse sold for more than five times the previous sale price after being held for 15 years. At 13 Ann Siang Road, a shophouse sold for more than 9.2% above the last price sale after being held for less than a year.

    Market outlook

    Buyers were most eager and active in the first half of 2021. Year 2020 was rough, but buyers were still more interested in buying shophouses than other real estate investments. In just six months, the total transaction value reached 91.6% of the entire year 2020 while the number of units transacted accounted for 81.4% of last year’s total.

    So barring any waves of infection and based on current demand momentum, it is more than likely that the sales amount for 2021 will exceed S$1.46 billion and that sales volume will cross the 200-unit mark.

    In addition to the high demand from buyers, we might also see an increase in shophouse sales in the second half of the year. With many sellers still keen to achieve a quick sale, prices could rise as buyers try to get a bargain. Inevitably, there will be a ceiling where the buyers will start to show resistance.

  • Strata Commercial and Retail (Market Updates Feb 2021)

    Strata Commercial and Retail (Market Updates Feb 2021)

    Strata Commercial

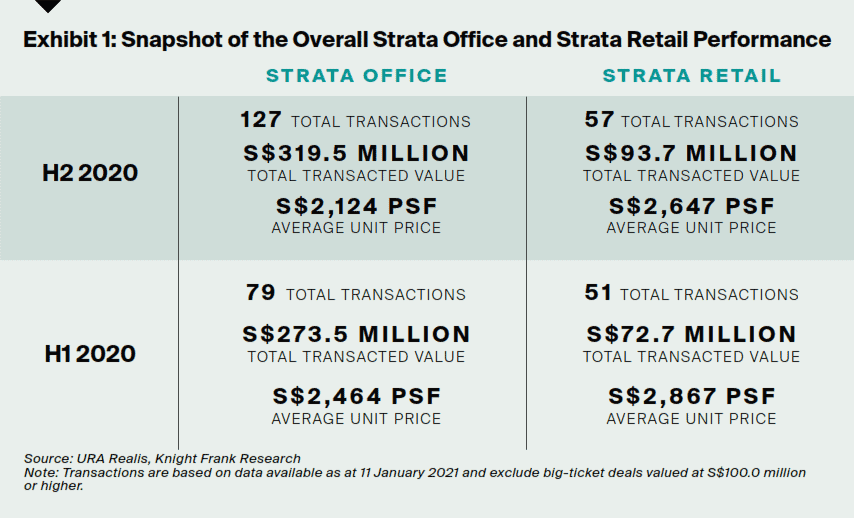
    Snapshot of overall strata office and strata retail performance

    STRATA OFFICE

    Overall performance
    • The total strata office transaction volume recovered to 127 units in H2 2020, after hitting a record low of 79 units (since H1 2009) in the first half of 2020. This brought full-year sales volume in 2020 to 206 units, some 34.4% lower than the 314 units sold in 2019. Out of the 206 units, 56 were smaller than 500 square feet (sq ft). Total sales volume in 2020 was also the lowest on record since 2003, as the COVID-19 pandemic impacted buyer’s sentiments in the strata office sector.
    • Strata office transaction value in H2 2020 increased by 16.8% half-yearly (h-o-h), totalling some S$319.5 million compared to S$273.5 million in H1 2020. However, the full-year transaction value in 2020 (S$593.0 million) was still 69.4% lower than the S$1,936.5 million recorded in 2019.
    • Strata offices located in the Central Business District (CBD) remained desirable and propped up sales amid the pandemic, with transactions in the Downtown Core accounting for some 59.7% (S$190.9 million) of the total sale value in H2 2020. The top five strata office transactions by price quantum in H2 2020 were also located in the Downtown Core. For instance, two units at Springleaf Tower exchanged hands for over S$20 million with the highest sales values during this period.
    • With limited new launches of strata offices in recent years, all 127 strata office units sold in H2 2020 were resale transactions. Strata office developments Woods Square in Woodlands Planning Area and Centrium Square in Kallang Planning Area obtainedtheir temporary occupation permits (TOP) in Q1 2020 and Q2 2020 respectively and continued to record resale transactions. There were 18 resale transactions in Centrium Square in H2 2020, making the Kallang Planning Area the second highest in terms of sales value totalling some S$43.0 million.
    • The average unit prices of strata offices declined by 13.8% h-o-h to S$2,124 per square foot (psf) on strata area in H2 For the entire year 2020, unit prices were generally stable with a slight uptick of 2.2% to S$2,268 psf compared to the whole of 2019.
    Comparing freehold and leasehold strata office performance
    • Both freehold and leasehold strata office units registered higher transaction volumes in H2 2020. There were 54 freehold and 73 leasehold units sold in the second half of 2020, compared to 36 freehold and 43 leasehold units in H1 2020.
    • Despite more leasehold units transacted in H2 2020, 48.0% fewer leasehold strata office units (116) were sold overall in 2020, compared to 223 in 2019. Freehold transaction volumes were largely unchanged, with 90 units exchanging hands in 2020, just one less than in 2019. Centrium Square accounted for 31 or about one-third of the freehold units sold in 2020.
    • The average unit prices for leasehold and freehold units also dipped in H22020 to S$2,115 psf (-12.4% h-o-h) and S$2,150 psf (-15.6% h-o-h) on strata area respectively. However, for the whole of 2020, leasehold unit prices rose by 9.2% year-on-year (y-o-y) to S$2,229 psf. This might be due to certain outlier sales, such as a strata office unit at Orchid Hotel that sold for S$7,657 psf.
    Transaction Volume and average unit prices of freehold and leasehold strata office units
    Market outlook

    In 2021, the strata office market together with the larger office sector in
    Singapore is expected to remain under pressure, with companies critically
    reviewing the way space is occupied in the post-pandemic era characterised
    by evolving remote work protocols. Therefore, transaction volumes as well
    as prices are likely to remain subdued for at least the first six months of the
    year. Nevertheless, as office users rationalise and right-size their space
    requirements, occupiers such as small enterprises may turn towards owner-occupied strata offices as a viable alternative to tenanted space.
    As such demand for strata offices, especially those in central locations, could improve in the second half of 2021.


    STRATA RETAIL

    Overall performance
    • As the pandemic upended the real estate market with the retail sector taking the brunt,the demand for strata retail spaces was severely weighed down. On a whole year basis, a total of 108 strata retail units totalling S$166.4 million exchanged hands in 2020, just half of the 205 units (S$343.9 million) sold in the previous year of 2019.
    • The declining demand for such strata retail space was further exacerbated by the acceleration of e-commerce that roiled retail businesses, pressurising many traditional shopowners to engage in unfamiliar virtual platforms. The phenomenon forced existing retail players to adopt omnichannel retailing strategies in efforts to remain relevant in a rapidly evolving industry, adapting to changes in consumer behaviour.
    Transaction Volume and average unit prices of freehold and leasehold strata retail units
    • In the second half of 2020, 57 strata retail units were sold for a total of S$93.7 million, representing an increase of 28.9% from S$72.7 million in H1 2020 which had a lesser 51 units (Exhibit 3). The onset of the reopening of the economy and enabling of physical viewings allowed for more sales, albeit at transaction volumes lower than in the same period a year ago where 91 units were transacted for some S$135.0million.
    • The average price of units transacted in H2 2020 narrowed from S$2,867 psf in H1 to S$2,647 psf. With the continued lack of new strata retail supply, activity in the market segment was driven by transactions in the secondary market.
    Comparing freehold and leasehold strata retail performance
    • The months of July to December 2020 registered the sale of 34 freehold strata retail units, a 47.8% increase from 23 units in the first six months of the year. This helped to raise the total transaction value by 147.3% from S$29.2 million in H1 2020 to S$72.2 million in H2. A notable deal included the sale of a Goldhill Shopping Centre unit spanning 1,087 sq ft for S$5.3 million.
    • Despite the more resilient performance of leasehold strata retail properties in H1 2020, demand fell to 23 units in H2, a 17.9% decrease from 28 units in the first half of the year. This brought the total transaction value to S$21.5 million, half of the value in H1 2020which recorded some S$43.5 million in sales. There was notable interest for strata retail units at Orchard Plaza, where four units on the second floor were sold from August to October 2020, with unit prices ranging from S$2,064 psf to S$2,860 psf.

    Market outlook

    • Moving forward, the global economic outlook remains uncertain with recurring infections in other nations despite the distribution of the vaccines. And even if vaccine distribution proves to be successful, prices of strata retail units in Singapore are envisaged to remain soft with more distressed sales expected due to the lack of tourists and safe distancing measures still in place.
    • The demand for such strata spaces is expected to come from proprietors that intend to run their own businesses, preferring to set up shop in locations where strata retail developments tend to be typically located. Often the lower costs when compared to renting retail space in a prime shopping mall in the same location act as the greatest incentive.
    • Thus, with the retail market gravitating towards more experiential placemaking strategies and migrating some of their services to digital platforms, there is a growing imperative for strata retail storeowners to also adopt similar ways to survive in a market that is in constant change.

    Taken from Knight Frank Singapore Strata Commercial Research Report. Click here if you wish to be added in our mailing list!

  • Do I need to renovate my property before I sell my property? Here’s why you MUST!

    Do I need to renovate my property before I sell my property? Here’s why you MUST!

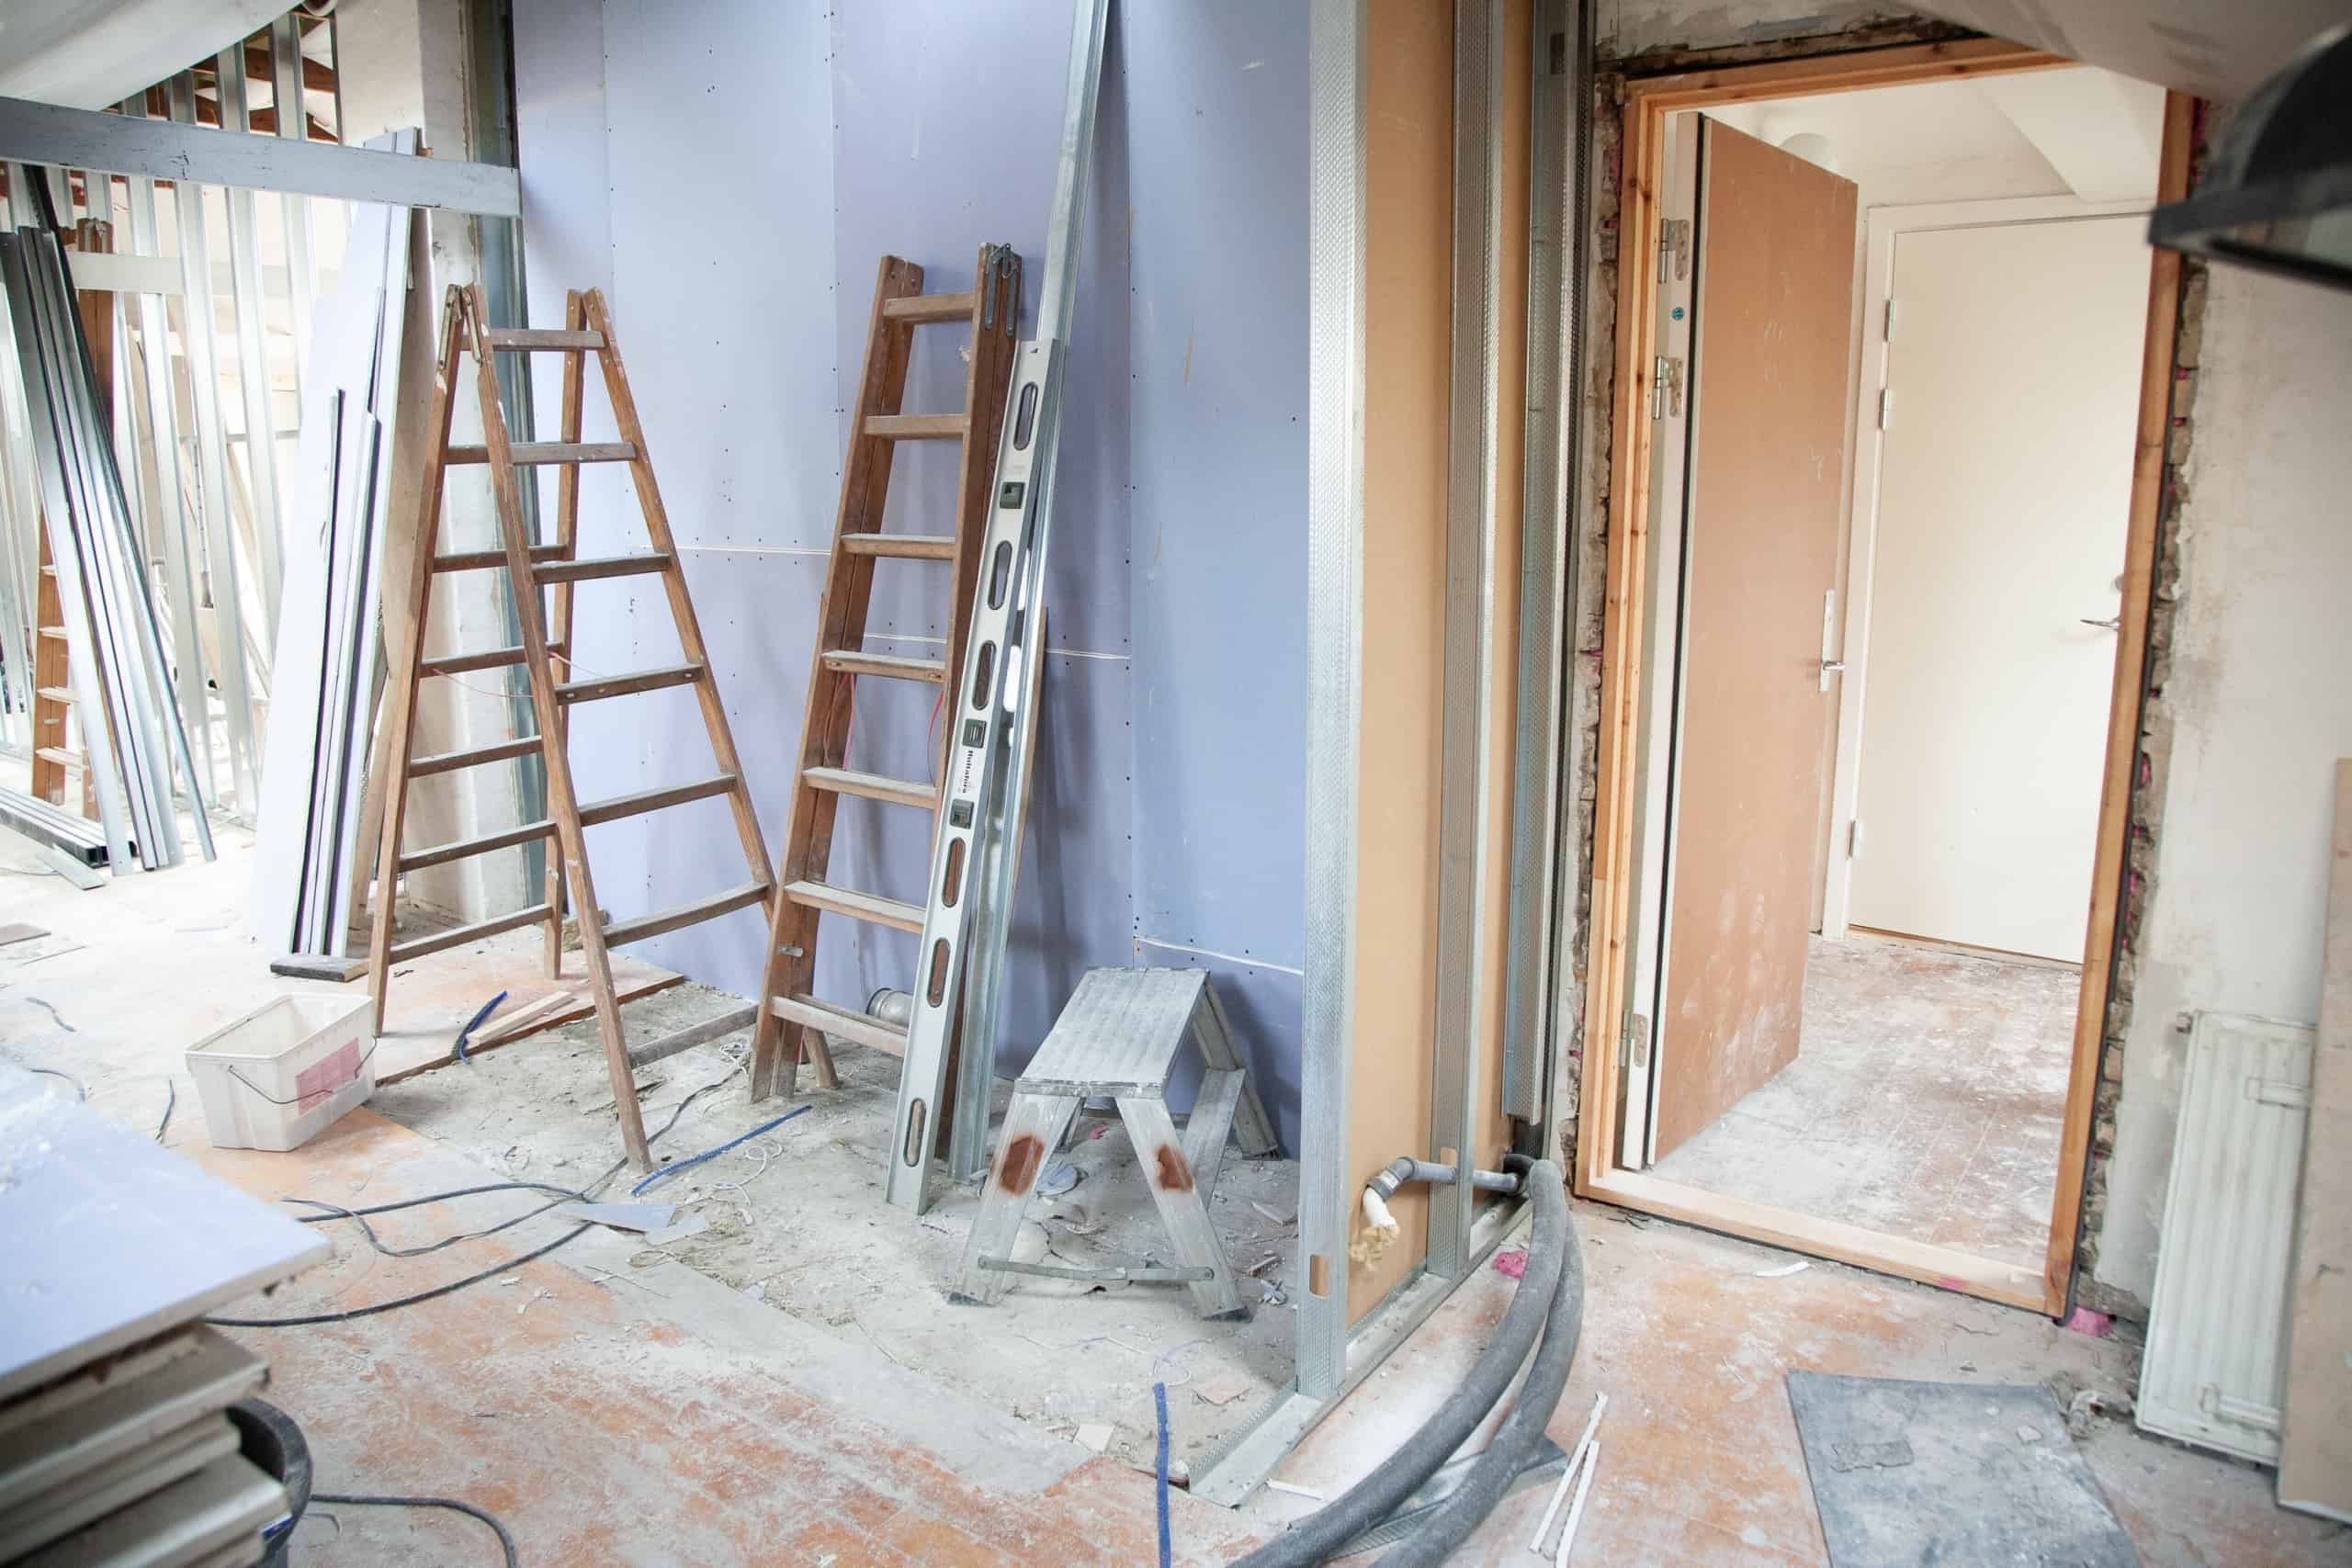
    Renovations could transform a drab property into your dream house. But everybody’s dreams are distinct, and the jury remains out on how renovations influence your property value.

    Before you begin hacking away in your walls, then it is worth it to think about the ways that the functions can impact the desirability of your house to potential buyers, and also to understand how to use renovations to your benefit to enhance your selling value.

    How renovations influence resale value 

    It’s hard to supply a precise estimate of just how much it could boost or decrease your house’s cost.

    However, what’s sure is that renovations do, in many instances, favorably impact resale value.

    It had been advised that through a resale condominium trade, an indicative valuation could be asked by a lien and the present status of the property (whether newly renovated or initial state ), would help determine the valuation.

    “In HDB trades, generally buyers are more inclined to pay a small premium to get a renovated apartment in contrast to your flat in its initial state.” as shared by an agent.

    But each purchaser differs. Typically, younger buyers tend to customise the house for their tastes and are consequently less worried about present renovations compared to having the ability to update the décor.


    It was noted that the buyers aged between 26 to 32 tend to choose for original-condition homes as the cost is reduced in comparison to renovated homes and they’re able to invest in their very own renovation. Buyers past that age group tend to go for homes which are in a move-in state with minor functions to be accomplished.”

    Also, it is essential to keep in mind that the value of your renovations will not continue forever. As a general guideline, recent, stylish renovations are somewhat more inclined to improve property value than elderly, outdated renovations, which might turn into a liability.

    “When the renovation has been completed 10 to 15 decades back, probably it is a responsibility as opposed to a characteristic of the home. Renovation design goes and comes, and with the majority of the buyers belonging to the younger audience, and some renovations over a decade old will probably be deemed conservative,” shared by Mr Kwek, an agent.

    Renovations that will boost your house’s resale value.

    1. Renovations only enhances your selling position if possible buyers enjoy them and would like to maintain them.

    It was noticed that a positive correlation involving property and renovations worth often, but warns that this is subject to how far the buyers enjoy the visual appeal of the house.

    “When the home is well remodeled, it provides the purchaser an excellent initial impression. This feel-good belief will enhance the opportunity for selling the home, rather than a home that’s in first state,” shared by Mr Han.

    2. Buyer loves to see the potentials of the units and simple renovation helps.

    It’s advisable in opting for non invasive, neutral-looking renovations instead of daring, polarising looks.

    “When it is done in a neutral motif with few built-in things such as attribute cabinets or walls, it would be a lot easier to market and at a much higher cost,” he states.

    What is the safest bet?

    “Minimalist for certain,” states Mr Kwek. “Fewer built-in things means more space for design creativity and not as much hacking the purchaser’s side.”

    Renovations which are possible buyer turn-offs 

    1.Bold and irregular designs

    Mr Kwek warns,”When the renovation is highly personalised with colour and design which caters mostly to the preferences of the vendor, it’s very likely to pull down prices or have difficulty finding a purchaser.”

    Vibrant colors might express your vibrant character, but they are a lousy thought when selling your house.

    “Walls which are Purple, green, or some other color that is powerful in character would create a poor first impression. What we need the purchaser to recall when they depart the device is the way bright, and it was, rather than because it’s a color that does not sit well together,” states Mr Kwek.

    2. Knocking down walls to merge rooms

    “Though it leaves the space considerably larger, usually it’s more disadvantageous than valuable. If a buyer wants to purchase a home with three bedrooms, it’s because they want three bedrooms.

    3. Open kitchens

    The same holds for open-concept kitchens that, while quite trendy at the moment, might be impractical for buyers who wish to perform plenty of heavy cooking.

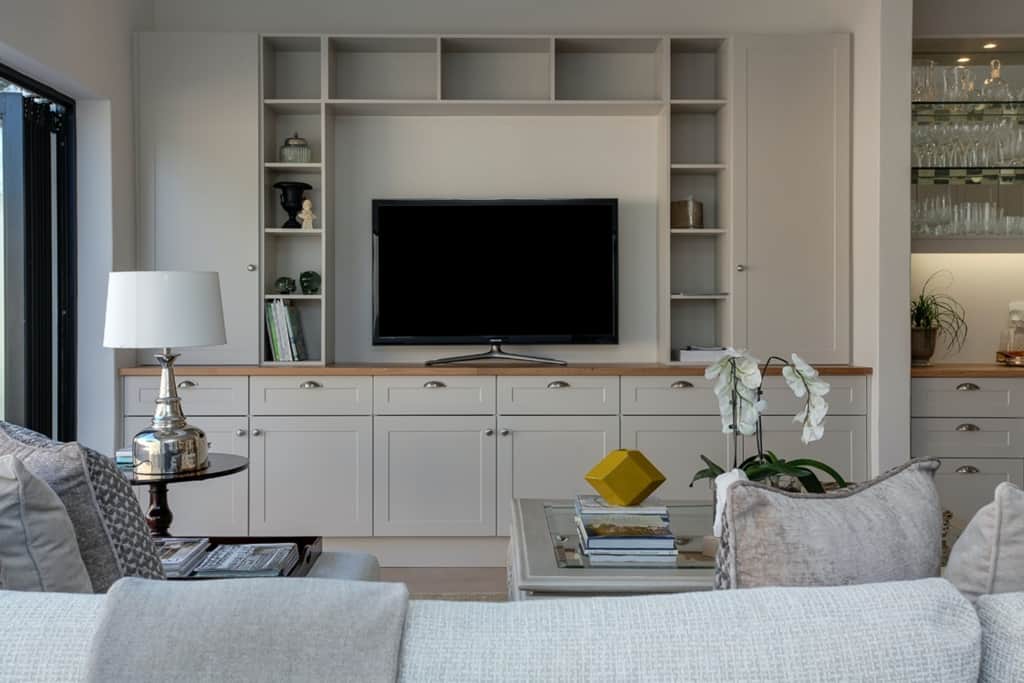
    4.Built-in carpentry

    Constructed carpentry might allow you to customise your furniture, however, it is not necessarily a fantastic idea when it is time to sell the house.

    “Too much built-in design function like research tables, beds or cabinets is sometimes not desired. Whether there are built-in cupboards, be certain they’re in impeccable condition. The design may not match the taste of the purchaser. Or they may be too old to maintain. To eliminate them might damage flooring that the purchaser plans to maintain,” warns Mr Han. 

    5. Wallpapers

    Wallpapers are just another no-no since it’s too much hassle to eliminate and maybe an overkill visually. As attractive to the greatest possible number of buyers is very likely to boost your advertising cost, it is a fantastic idea to go for renovations which will interest the masses–minimalist with a lot of white.

    Conclusion: Renovations can be very subjective. 

    Popular layouts are highly seasonal, and mature renovations which are no more trendy can turn into a liability.

    Highly personalised renovations can also lower your asking price because buyers may want to eliminate them. After all, in the event that you revived your home to express your distinctive character, it is not unreasonable to presume that buyers will wish to do precisely the same.

    The majority of the brokers surveyed stated that buyers tend to inspect floors, the kitchen and baths throughout home screening sessions since these will be the most expensive areas to overhaul. That been said, it is more about performance than aesthetics.

    It was noted that the kitchen and bathroom are inclined to be places that a number of the customers desire to redesign, so rather than obsessing about the plan, it might be worthwhile to make sure these places are in good shape and all stains, water flows and unevenness are eliminated.

    Thus, inspect carpentry beneath the washing regions, assess the ceiling for escapes, test the water pressure of their faucets and hope for the best.

    Tips for sellers looking to sell their place

    Declutter — Eliminate unwanted things and whatever appears worn out or broken. Buyers often favour a chic, bright and airy appearance that is free of clutter.

    Repaint – A new coat of paint could immediately make your house appear fresher and more modern.

    Replace broken floors — Potential buyers tend to inspect floors for abuse and unevenness. If yours is profoundly damaged, it is possible to opt for cheaper materials such as vinyl or laminate.

    Bleach and wash bathroom — A filthy bathroom is an immediate turn-off, so wash and bleach it before seeing sessions.

  • Pair Of Freehold Shophouses At Bukit Pasoh For Sale At From $35 Mil

    Pair Of Freehold Shophouses At Bukit Pasoh For Sale At From $35 Mil

    There were at least three shophouses along Bukit Pasoh Road are set up for sale over the past week, as the sales of shophouses show no indication of slowing. The newest is a set of adjacent shophouses, 44 and 46 Bukit Pasoh Road, situated near Outram Park MRT, that have been set up for sale with a guide price of S$35 million, Knight Frank Singapore stated in a press announcement on Monday.

    The set of freehold shophouses have a built-up area of around 10,078 sqft and combined lead area of approximately 4,745 sqft. It’s about $3,473 per sqft, based on built-up area.

    The conservation shophouses at 44 & 46 Bukit Pasoh are leased to two restaurants. (Picture: Knight Frank)

    Knight Frank explained the land is available to both foreign and local buyers, and there isn’t any extra purchaser’s stamp duty levied. According to Knight Frank, the floor and second floors of this shophouses are rented to 2 restaurants, whereas the upper floor is available for rent. It added that the land could be transformed into a resort, subject to authorities approval. “We’ve seen demand increase for shophouses in prime Districts 1 and 2 because Singapore exited the ‘circuit breaker’ at June 2020, even as most search safe-haven resources in a secure environment” explained Ian Loh, head of capital markets for land and construction, collective and strata earnings at Knight Frank Singapore. “Within the past couple of months, we’ve received a constant flow of enquiries from high-net-worth households, investors and end-users, which has translated into the conclusion of many shophouse trades,” he added.

    The set would be the newest in a rising amount of shophouses set up available in recent months, after a lull on the marketplace from pandemic-related restrictions. Three shophouses along New Bridge Road also have been set up for sale this past month, including one home Song Fa Bak Kut Teh’s flagship socket that was set up for sale on Monday.